

What Does Collision Insurance Cover?
Fausto Bucheli Jr
President/Owner of Cheap Insurance Agency
Meet Fausto, the President and Owner of CheapInsurance.com.
CA license number 0E59876, NPN: 8282775
With an MBA in Marketing and a licensed insurance broker in California, Fausto is a trusted source in the insurance industry.
His deep knowledge of car insurance, especially in the automotive sector, allows him to effectively understand and address customer challenges.
At CheapInsurance.com, Fausto's mission is to educate customers, help them find the best coverage at the right price, and connect them with reputable insurance carriers.
With a passion for marketing, Fausto leverages his skills and industry expertise to bridge the gap between customers and outstanding insurance options.
Through sharing his knowledge, he empowers customers to make informed car insurance decisions.
When you choose CheapInsurance.com, you can trust that Fausto and his team will guide you toward the best car insurance coverage, ensuring peace of mind and protection on the road ahead.
John Davey
Informations Systems Administrator at CheapInsurance.com
Meet John, a trusted member of CheapInsurance.com since 1998.
With extensive experience in designing information systems and insurance industry tools, John ensures seamless operations and efficient workflows.
His expertise spans from legacy systems to modern technology, including comparative quoting and agency management systems.
Beyond his professional achievements, John actively contributes to his community as a vice president on a nonprofit's board of directors and through various advisory committees.
Trust John's wealth of knowledge and commitment to finding the right car insurance coverage for your needs at CheapInsurance.com.
Reviewed By
QUICK ANSWER
Collision insurance pays for repairs to your own vehicle if you hit another car, a stationary object like a pole, or if your car flips in a single-car accident. Unlike liability coverage, which pays for damage you cause to others, collision is optional unless a lender requires it. It covers up to the actual cash value of your car minus your deductible, making it essential for protecting financed vehicles.
Real-World Scenarios
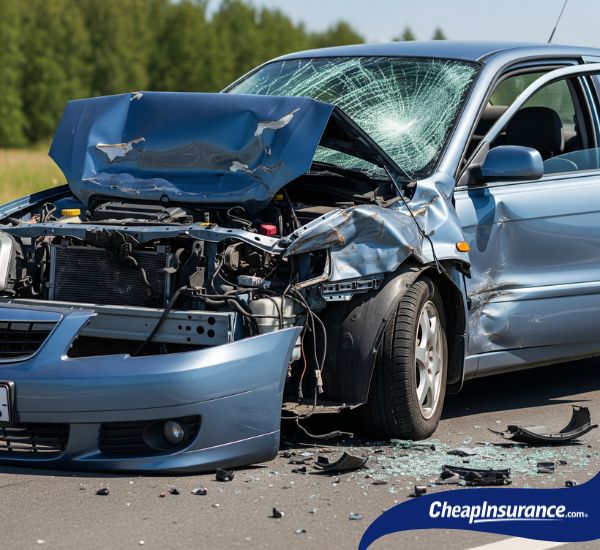
Collision insurance provides a financial safety net for damage to your own vehicle, regardless of who causes the accident. It typically steps in during these common situations:
Single-Vehicle Accidents: You lose traction on an icy road and hit a telephone pole, or your vehicle flips over after you swerve to avoid an animal.
Object Impacts: You hit a massive pothole that ruins your suspension, or you accidentally back into a high concrete bollard in a parking garage.
Hit-and-Runs: Another driver sideswipes your parked car while you’re in the grocery store and drives off without leaving a note.
Standard Multi-Car Crashes: You cause a “fender bender” with another driver and need to repair your own front bumper.
Understanding The Payout
Unlike liability insurance, where you select a specific coverage limit (e.g., $50,000), the Actual Cash Value (ACV) of your car dictates your collision coverage.
Key Note: If the cost to repair your vehicle exceeds its current market value, the insurance company will “total” the car and pay you its depreciated value, minus your chosen deductible.
CheapInsurance.com by the Numbers
50+
Years of Experience
50+
Insurance Options
50
States Served
$821
Avg. Annual Savings
5M+
Customers Helped
3min
Avg. Quote Time
Data Analysis: Annual Savings from Car Insurance Comparison Sites
Understanding Actual Cash Value (ACV)
ACV is not what you paid for the car three years ago. It isn’t the price of a brand-new model either. It is the market value of your car the second before the accident happened. Car insurers take the replacement cost and drop it based on mileage, wear, and age. If your car is totaled, this is the maximum check you will get, minus your deductible.
Collision vs. Comprehensive: The Quick Divide
These two are often bundled as “full coverage,” but they handle different risks.
Collision coverage: Accidents that involve other cars and stationary objects.
Comprehensive coverage: Events out of your control like hail, theft, fire, or hitting an animal.
Video Transcript
The following is a transcript of the video above. It has been lightly formatted for readability.
So, you’ve got your state-mandated liability insurance. You’re legal on the road, and then crunch. You back into a concrete pillar in a parking garage. Or even worse, you’re the one who rear-ends someone at a stoplight.
It’s a bad day, but it’s about to get worse if you realize that your liability insurance doesn’t actually cover your car. It only covers the other person’s bumper.
That is a huge wake-up call for a lot of drivers. If you want your own repairs paid for, you need to talk about collision insurance.
Exactly. Collision is the part of your policy that pays to repair or replace your vehicle if you hit an object like a fence or a pole or another car, regardless of who was at fault.
Wait, even if it’s 100% my fault, the insurance company still cuts me a check?
Yes, that’s exactly what you’re paying for. Whether you slide on ice into a guardrail or you’re involved in a multi-car pileup, collision is what saves your own car from the scrap heap.
It even covers hit-and-runs, right? Like if I come out of the store and my door is smashed in?
It does, but there’s a key detail people often forget: the deductible. Unlike liability, you almost always have to pay your $500 or $1,000 out of pocket first before the insurance company pays the rest.
Now, is this required? Because I know it can be a bit more expensive than just having liability.
If you own your car outright, the state doesn’t care if you protect it, so it’s optional. But if you have a loan or a lease, your bank is going to mandate that you carry collision. They want to make sure their investment is protected.
What if the repair costs more than the car is actually worth?
Then the insurance company will total the car. They’ll give you a check for the actual cash value—basically, what the car was worth the second before the crash minus your deductible.
So, if I’m driving an old clunker worth maybe $1,500, and my deductible is $1,000…
Then collision might not be worth the cost. You’d be paying a premium for a maximum payout of only $500. At that point, many drivers drop collision to save money.
But if you’re driving a newer car or something you couldn’t afford to replace tomorrow, collision is pretty much essential. It’s the difference between a minor setback and a total financial disaster.
If you’re trying to figure out if collision is worth it for your specific car, or if you just want to find a better rate, you got to check out CheapInsurance.com.
We show you the with and without cost side by side so you can make the smartest choice for your wallet.
Knowledge is the only thing that actually lowers your risk. I’m Tito.
And I’m Jaclyn.
Drive safe, keep it between the lines, and we’ll see you at CheapInsurance.com.
Fausto Bucheli Jr, licensed insurance broker and owner of CheapInsurance.com recommends: “Collision and comprehensive coverage should protect your financial stability. If your car is older and paid off, adjusting or removing these coverages can reduce your car insurance costs by hundreds of dollars per year without increasing financial risk.”

When Should You Buy Collision Insurance?
Since collision insurance is optional, you have to weigh the cost.
Lienholders: If you finance or lease, your bank loan will demand both collision and comprehensive. They want to protect their loan on the asset.
Newer Vehicles: If you drive one of many expensive vehicles on the road today, a total loss could be a financial disaster.
Older Cars: If your car is only worth $2,000 and your deductible is $1,000, you might be paying more in premiums than the car is worth. At that point, many drivers drop the coverage to get cheapinsurance.
Is Lost Key Replacement Covered By Auto Insurance?
Standard auto insurance does not cover lost car keys, but coverage applies in three specific scenarios depending on the policy: stolen keys via Comprehensive Coverage, lockouts via Roadside Assistance, and full replacement via a Key Replacement Rider.
Comprehensive Coverage (Stolen Keys Only): Pays for replacement keys only if someone steals them and you report the theft to the police. Key Catch: Standard policy deductibles apply. If the key costs $400 and your deductible is $500, insurance pays $0.
Roadside Assistance (Lockout Entry Only): Pays for a locksmith to unlock the vehicle or tow it. Key Catch: Covers car access only; it does not pay to manufacture or program a new key or fob.
Key Replacement Add-On (Full Key & Fob Protection): An optional policy rider specifically designed to cover lost, stolen, or damaged fobs and keys, usually with a low or $0 deductible.
Is Paintless Dent Repair Covered By An Insurance Policy?
Yes, Comprehensive Auto Insurance covers Paintless Dent Repair (PDR) for non-collision damage like hail, falling branches, and vandalism.
Comprehensive Coverage: Fully reimburses non-collision events such as hail storms, falling debris, and vandalism. Insurers mandate or prefer PDR for hail because it preserves factory paint, restores value, and costs less than traditional bodywork.
Collision Coverage (Impact Dings): Reimburses PDR for crash damage, stray shopping carts, or parking lot door dings.
Liability Only Policies: Covers third-party damage only. Offers zero reimbursement for PDR on your vehicle.
The Cost Factors
Insurance premiums are not a random number. Insurers base them on your driving history, your location or ZIP code, and the value of your car. Your deductible also plays a huge role. A $1,000 deductible makes your monthly bill lower, but it means you need to have that cash ready if you ever have an accident.
While state laws mandate minimum liability coverage, they don’t require you to protect your own car. You make that choice optionally. Still, most people across the country add collision and comprehensive to their policies. This is because liability only pays for the other person’s mistakes. Collision insurance is what actually pays to fix or replace your own ride after a wreck.
It is good to explore the mechanics of this coverage. It will help you decide if the cost is worth the benefit when you are looking for car insurance quotes.
The Basics: What Does Collision Coverage Actually Do?
Collision coverage pays for damage to your car after you hit another vehicle or an object. It does not matter who caused the crash. You could rear-end a truck or slide into a guardrail on a rainy night; collision covers both.
The Role Of The Deductible
Unlike liability, collision coverage almost always comes with a deductible, the amount you pay out-of-pocket before the insurance company cuts a check.
Higher Deductible lowers your monthly premium but costs more during an accident.
Lower Deductible increases your premium but provides more immediate relief if you wreck.
Founded in California in 1974 as an insurance agency, CheapInsurance.com has spent decades helping people find affordable coverage.
Over time, we became one of the first brokerages to go online in 1998, making insurance shopping faster and easier. Our mission has always been simple: insurance is a basic necessity, not a luxury. Specifically, our technology quickly scans the marketplace in seconds, compares rates, and uncovers discounts you might otherwise miss. Additionally, we explain coverage in clear, simple terms.
Because of this, people get real options and can avoid overpaying for features they do not need, while still maintaining strong, reliable protection.
Frequently Asked Questions About Collision Insurance
What does collision insurance cover?
Collision insurance helps pay for damage to your own vehicle when you collide with another car or object, such as a pole, guardrail, or fence. Coverage applies regardless of who is at fault and pays for repairs or replacement of your car up to its actual cash value, minus your deductible.
Is collision insurance required by law?
Collision insurance is not required by state law. However, lenders and leasing companies usually require it if your vehicle is financed or leased. Many drivers also choose collision coverage voluntarily to avoid paying out of pocket for expensive repairs after an accident.
Does collision insurance cover hit-and-run accidents?
Yes. Collision coverage generally pays for damage to your vehicle caused by a hit-and-run accident. You would still be responsible for your deductible, but collision insurance can help cover repairs even if the other driver cannot be identified.